What is the scope and industry significance of the Government Procurement Tool Market?
The Government Procurement Tool Market represents a critical digital transformation sector, valued at $9.65 Billion in 2026. Our analysis indicates this market governs public-sector spending across federal, state, and municipal agencies, enforcing strict compliance with regulatory bodies like the Federal Acquisition Regulation (FAR) while managing complex RFPs and multi-million-dollar defense logistics.
Key market drivers, restraints, challenges, and opportunities shaping Government Procurement Tool Market
Market expansion is heavily driven by mandates for fiscal transparency and anti-corruption measures in public administration. However, integration friction with legacy municipal ERP systems and stringent data residency laws pose notable restraints. Opportunities abound in automating supplier risk assessment and integrating AI-driven spend analysis for federal healthcare and defense agencies.
Emerging trends and growth patterns in Government Procurement Tool Market
The shift toward cloud-native architectures and automated supplier qualification workflows is redefining public sector operations. Our research shows agencies increasingly adopt advanced procurement analytics to track budget variances in real time, shifting away from reactive auditing toward predictive spend classification across education and transportation sectors.
COVID-19 impact analysis — how the pandemic affected Government Procurement Tool Market and the recovery trajectory
The pandemic acted as an unprecedented catalyst, forcing emergency procurement frameworks to migrate online overnight. Agencies urgently deployed electronic tendering and e-invoicing platforms to manage rapid PPE acquisition for healthcare systems. This crisis-driven adoption established a permanent baseline for modern digital procurement recovery trajectories.
Competitive landscape — major players, market concentration, and strategic dynamics
The competitive ecosystem features enterprise giants like SAP SE, Oracle Corporation, and Coupa Software Inc. competing alongside specialized public sector innovators such as Tyler Technologies Inc., OpenGov Inc., and Euna Solutions. Market concentration is moderate-to-high, with industry leaders deploying strategic acquisitions to capture state and local government contracts.
Executive summary — high-level synthesis of key findings about Government Procurement Tool Market
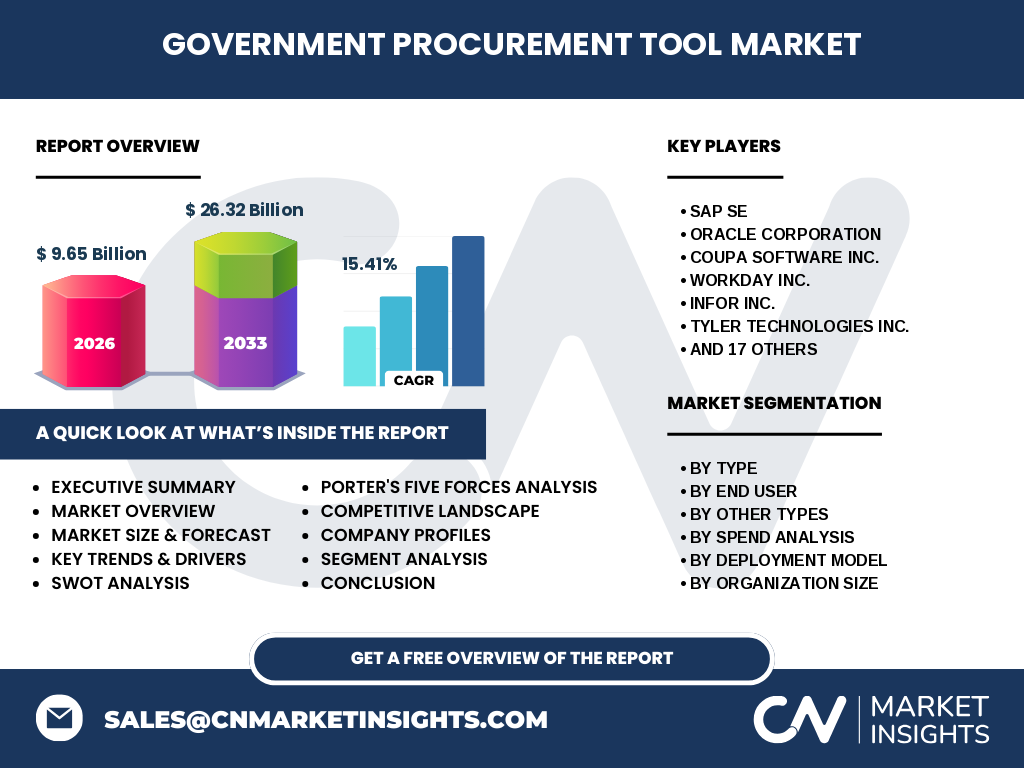
Driven by robust digital modernization initiatives, the Government Procurement Tool Market is projected to surge from $9.65 Billion in 2026 to $26.32 Billion by 2033, achieving a remarkable CAGR of 15.41%. Adoption is concentrated in cloud-based deployment models that ensure regulatory compliance and optimize supplier management.
Market forecast — projected growth from 2027 to 2033
Our forecasting models project aggressive expansion through the 2027-2033 window, scaling the market from its 2026 baseline of $9.65 Billion to a substantial $26.32 Billion by 2033 at a 15.41% CAGR. This trajectory reflects sustained global investments in electronic procurement and rigorous contract compliance tracking.
Segmentation analysis — break down each segment category, explain what it covers and its market role
The market is segmented by type (Electronic Procurement, Vendor Management, Contract Management, Spend Analysis), deployment model (Cloud Based, On Premises, Hybrid), organization size (SMEs, Large Enterprises), and end user (Defense, Healthcare, Education, Transportation, Public Administration). Each segment targets specific workflows, from supplier registration to budget variance analysis.
Regional market analysis — geographic distribution and performance across regions
Geographic performance is heavily skewed toward North America and Europe, underpinned by stringent public spending transparency laws and established digital governance frameworks. Meanwhile, Asia-Pacific exhibits high-potential growth due to rapid e-government infrastructure investments across emerging economies.
In-depth regional review — detailed examination of key regional markets
North America dominates demand, propelled by federal mandates requiring automated electronic sourcing and robust supplier risk assessment tools. Europe follows closely, driven by European Union directives on public procurement transparency, favoring specialized platforms from vendors like Basware Oyj and Proactis Holdings plc.
Company profiles — strategic positioning of leading companies in Government Procurement Tool Market
Industry leaders maintain distinct strategic positioning. JAGGAER LLC and Ivalua Inc. focus on deep enterprise sourcing and spend analytics, while Tyler Technologies Inc. and OpenGov Inc. tailor their contract and financial management suites specifically for state and local public administration entities.
Porter's Five Forces analysis — competitive forces assessment
Supplier power remains moderate due to standardized API integrations, while buyer power is high given rigorous government RFP standards. Threat of substitutes is low owing to specialized regulatory requirements, but competitive rivalry is intense among established enterprise providers and agile GovTech specialists.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Key strengths include high customer retention and mission-critical utility. Weaknesses involve lengthy bureaucratic sales cycles. Opportunities lie in expanding catalogue management and AI-driven requisition workflows. Threats center on cybersecurity vulnerabilities and complex regulatory shifts across jurisdictions.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain flows from core software development infrastructure to specialized procurement modules like electronic tendering and supplier performance tracking. Value is delivered directly to public sector end-users, ensuring audit-ready compliance for defense, healthcare, and educational institutions.
Investment insights — strategic recommendations and high-potential areas
Investors should prioritize companies offering integrated cloud-based spend classification and automated supplier risk assessment modules. Capitalizing on the 15.41% CAGR requires backing firms with proven past performance in federal and municipal procurement deployments.
Conclusion and key takeaways
The Government Procurement Tool Market is on a definitive growth path, reaching $26.32 Billion by 2033. Strategic focus on cloud deployment, robust contract repositories, and comprehensive spend analysis will differentiate market leaders from legacy competitors.
Research methodology — detail how baseline estimates are triangulated
Our findings are triangulated by combining exhaustive public tender registry data, primary stakeholder interviews with chief procurement officers, and secondary macroeconomic indicators from global trade and public administration databases to establish the 2026 baseline of $9.65 Billion.
Scope of the report — coverage parameters and limitations
This report covers global deployment models across electronic procurement, vendor management, contract management, and spend analysis tools. Limitations include potential delays in municipal budget reporting and varying international definitions of public administration expenditures.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent market activity highlights major players like Coupa Software Inc. and Zycus Inc. launching AI-powered contract compliance tracking tools. Additionally, strategic partnerships between tech innovators and government contractors aim to streamline electronic invoicing and secure public sector supply chains.